Master the Grace Period: Powerful Strategies to Maximize Credit Card Grace Periods & Insurance Benefits. Every month, millions of American cardholders leave money on the table.
Between high interest charges, missed insurance coverage windows, and misunderstood billing cycles, credit card users routinely pay extra for benefits they could easily get for free.
Learning how to leverage your credit card’s grace period alongside built-in credit card insurance benefits transforms your credit card from a potential debt trap into a powerful financial protection tool.
This comprehensive guide breaks down how grace periods work, how to align them with built-in purchase and travel protections, and the exact strategies you need to keep your money safe.
Executive Summary / Key Takeaways
- Grace Periods Eliminate Interest: The grace period is the window between the end of your billing cycle and your payment due date. If you pay your statement balance in full, you pay zero interest.
- Built-in Insurance Requires Strict Activation: Most card benefits—such as rental car collision coverage, trip delay insurance, and purchase protection—only activate if you charge the eligible purchase in full (or partially) to that specific card.
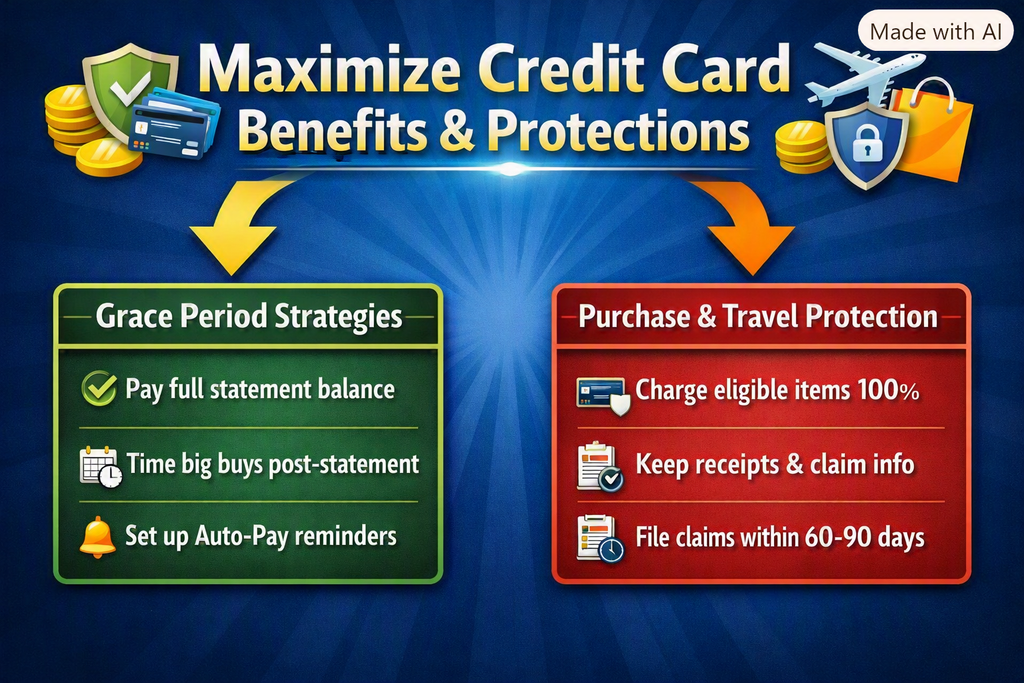
- Filing Deadlines Are Critical: Insurance claims tied to purchase or travel disruptions have strict filing windows (often 60 to 90 days).
- Automated Management Shields Your Credit Score: Setting up automatic payments for the full balance ensures you maintain your interest-free grace period month after month.
Understanding the Credit Card Grace Period
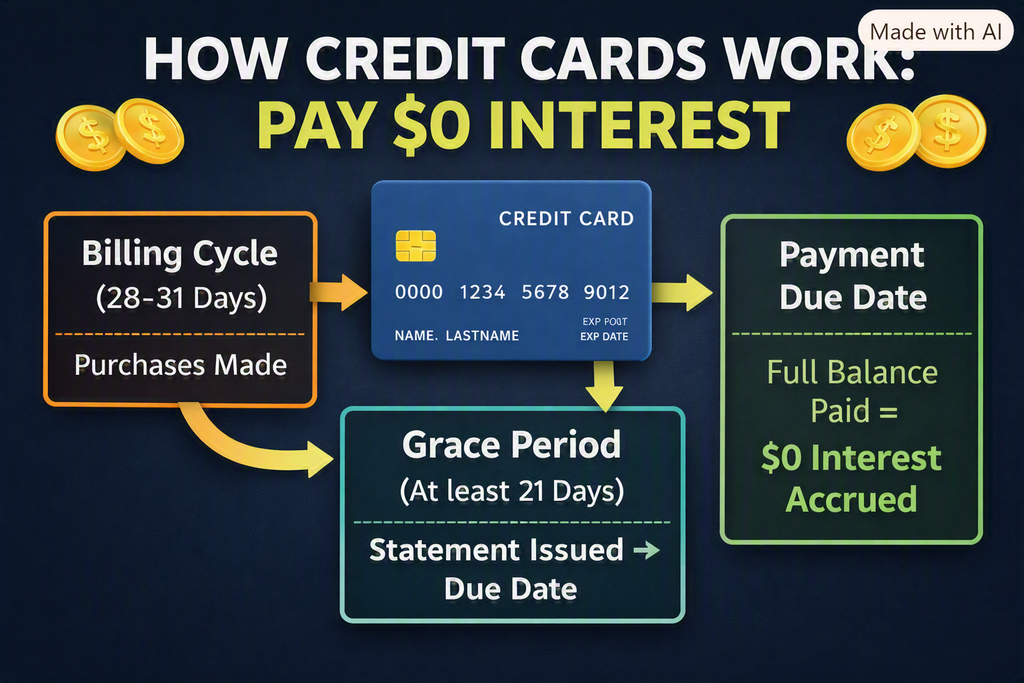
A credit card grace period is the time frame during which you are not charged interest on new purchases, provided you paid your previous statement balance in full by the due date.
Under U.S. consumer protection laws (such as the CARD Act), if a credit card issuer offers a grace period, it must be at least 21 days long from the date your billing statement is delivered.
How the Interest-Free Window Works
If your billing cycle runs from January 1 to January 31, your statement balance reflects all charges made in that period. If your payment due date is February 22, the period between January 31 and February 22 is your grace period. Pay the full statement balance by February 22, and no interest will accrue on those January purchases.
Important Note: Carrying a balance past the due date revokes your grace period. Interest starts accruing immediately on all new purchases until the full balance is paid off across consecutive billing cycles.
Strategies to Maximize Credit Card Grace Periods & Insurance Benefits
To get the most value out of your credit cards, combine interest-free timing strategies with built-in card protections.
1. Time Large Purchases Right After Your Statement Closes
If you plan to buy a major appliance or book an expensive vacation, wait until a day or two after your billing statement closes. This shifts the charge onto the next billing cycle, effectively giving you up to 50 days (a 30-day billing cycle + 21-day grace period) to pay off the purchase without incurring interest charges.
2. Match the Right Card to the Right Insurance Coverage
Not all cards offer identical built-in protections:
- Travel Cards: Best for booking flights and hotels because they offer trip delay, lost luggage, and rental car collision damage waivers.
- Retail / Premium Consumer Cards: Best for high-ticket electronics, appliances, or luxury goods due to extended warranty and purchase protection against theft or accidental damage.
Practical Steps to Leverage Your Grace Period
Setting Deadlines and Payment Goals
- Automate the Full Statement Balance: Set up Auto-Pay through your bank account for the Full Statement Balance (not the Minimum Due) to ensure you never lose your interest-free status.
- Calendar Reminders: Align your payment due dates with your payday schedule. Most U.S. card issuers allow you to change your monthly due date online or via customer service.
Continuous Balance Monitoring
- Set Up Instant Alerts: Use your card issuer’s mobile app to receive push notifications for every purchase over a set dollar amount.
- Track Utilization: Keep your total balance under 30% (ideally under 10%) of your available credit line to protect your credit score.
Flexible Options for Debt Management
If you carry a balance and lose your grace period, regain control quickly:
- 0% APR Balance Transfer Cards: Transfer existing balances to a card offering a 0% introductory APR window (often 12 to 21 months) to eliminate interest while paying down principal.
- Targeted Debt Payoff Methods: Use the Snowball Method (paying smallest balances first for psychological momentum) or the Avalanche Method (paying highest-interest balances first for maximum mathematical savings).
Explicit Benefits of Mastering Grace Periods
1. Absolute Protection Against Interest and Fees
Paying off your statement balance in full within the grace period guarantees you enjoy credit flexibility, security, and cash back rewards without paying interest fees.
2. Avoidance of Additional Financial Costs
Failing to pay by the due date results in late payment fees (up to $41) and penalty APRs that can spike your interest rate above 29.99%. Mastering your payment schedule keeps these costs at zero.
3. Credit Score Optimization
Payment history accounts for 35% of your FICO® Score, while credit utilization accounts for 30%. Paying on time and maintaining low balances directly improves your credit rating over time.
Enhancing Your Understanding of Credit Card Insurance
Many cardholders purchase third-party protection policies without realizing their credit card already includes built-in coverage.
Accidental Purchase Coverage & Loss/Damage Protection
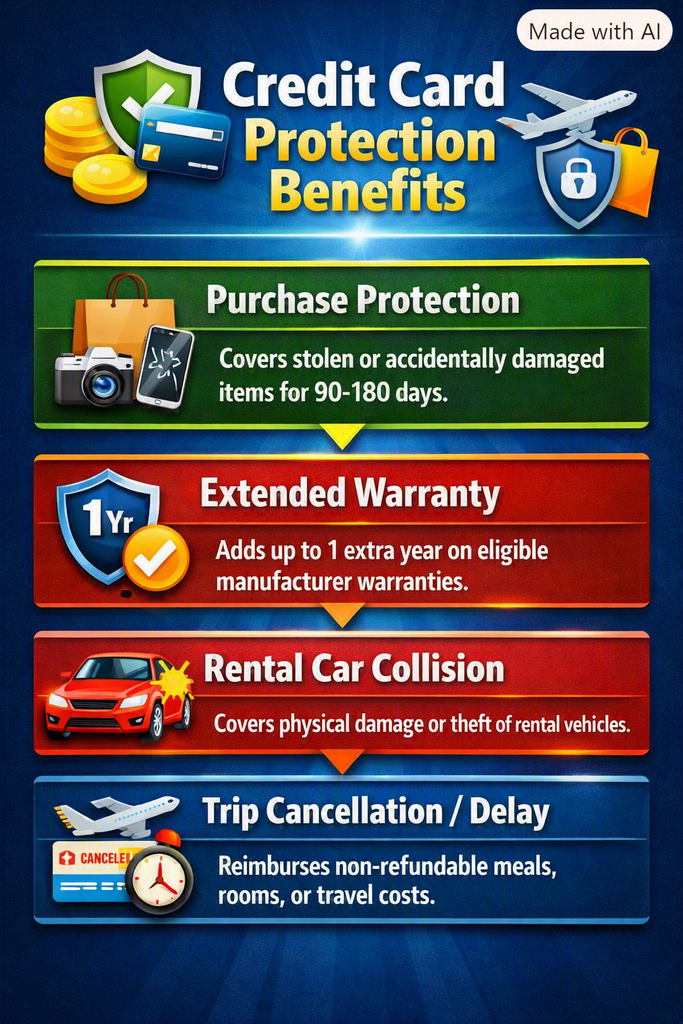
- Purchase Protection: Covers eligible new purchases against accidental damage or theft for 90 to 180 days from the purchase date.
- Extended Warranty: Automatically doubles or extends the original manufacturer’s warranty (typically by up to 1 additional year) on eligible items paid for with the card.
Ensuring Financial Peace of Mind
Built-in travel perks—such as secondary/primary auto rental coverage, trip cancellation reimbursement, and lost luggage insurance—save you hundreds of dollars per trip when unexpected travel disruptions occur.
Frequently Asked Questions (FAQ)
What is a credit card grace period?
A grace period is the number of days between the end of your credit card billing cycle and your payment due date (at least 21 days in the U.S.). During this period, you are not charged interest on new purchases if you paid your previous statement balance in full.
How can I make the most of grace periods?
To maximize your grace period, pay your entire statement balance before the due date every month. Time large purchases right after your statement closing date to give yourself up to 50 days to pay without accruing interest.
What should I do if I need insurance coverage during a grace period?
Credit card insurance benefits (like purchase protection or travel delay coverage) remain active as long as your account is in good standing and you paid for the eligible item or trip with that card. If an incident occurs, save all receipts and contact your card’s Benefits Administrator to initiate a claim immediately.
Why is it important to understand grace period strategies?
Understanding grace periods helps you avoid expensive interest charges, lower your debt-to-credit ratio, boost your credit score, and utilize built-in purchase and travel protections without spending extra money on standalone insurance plans.
Where can I find detailed information about my card’s insurance benefits?
You can find full coverage limits, terms, and claim filing deadlines in your credit card’s official Guide to Benefits. This document is accessible by logging into your card issuer’s website or mobile application, or by calling the customer service number on the back of your card.
Deixe um comentário